
President Trump declared a national economic emergency and hit the world with a fresh wave of tariffs. It’s the kind of news cycle that seems unrelated to AI. But what if it’s exactly the opposite?
This week, a new foresight scenario AI 2027 landed with a jolt. Daniel Kokotajlo and colleagues paint a picture of how the next three years of AI development might unfold. They describe the emergence of successive generations of superhuman AI agents—from powerful code-generators to artificial researchers operating at 50x human speed. And crucially, they assume an unbroken pipeline of physical and economic inputs: compute, power, capital and institutional capacity.

But what if those assumptions break down?
The tariff announcements are the first steps toward a new geoeconomic settlement, ending the era of peak globalisation.
Taiwan, which produces the vast majority of advanced logic chips including Nvidia’s GPUs, now faces a 32% reciprocal tariff on many goods. South Korea, a key source of memory chips, sees 25%. While raw semiconductors themselves are strategically excluded, the equipment housing them — servers and accelerator modules assembled in Taiwan, China (34%), Mexico (10%+) or Vietnam (46%) — is not.
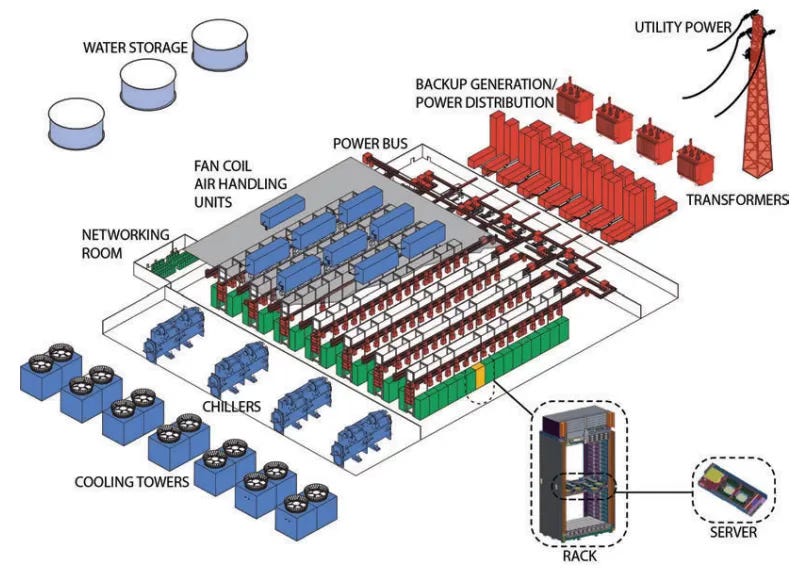
How significant is this? Consider a simplified data centre cost breakdown: 50% for compute hardware, 15% for cooling systems, 15% for build-out (steel, racks, power) and 20% for land. Land isn’t directly hit, and raw chips and copper are excluded. But tariffs on imported compute hardware could increase that dominant 50% portion by nearly 25%. Cooling and structural materials—like steel—face tariffs too. Cumulatively, these measures could raise the total cost of a cutting-edge AI data centre by 15–17% or more.
This friction hits at a delicate time. Executives and investors, many of whom built careers under globalisation doctrine, are confronting an unfamiliar world. The world economy may eventually settle into new regional blocs and bilateral pacts. But for now, uncertainty is real. Firms are revising assumptions, rethinking supply chains and pausing investment. There’s been action from the White House, but we haven’t seen the reaction of the bosses who will make the investments.
The material weight of intelligence
Pre-tariffs, state-of-the-art AI campuses could cost $20 million per megawatt to construct—meaning a 2 GW cluster might cost $40 billion. With tariffs, those projects may now face multi-billion dollar cost increases, practically overnight.
That alone is a headwind. Add macroeconomic cooling, and investment becomes more precarious. As consumer spending and corporate confidence dip, the big tech firms may think twice before embarking on aggressive infrastructure buildout. Share prices fall. CFOs get cautious. Even existential urgency can’t outpace physics or finance.